Cash Flow Forecast Mistakes New Businesses Make: From Flat Sales To Double-Counting Costs
A cash flow forecast shows how money is expected to move through a new business month by month. Small errors can hide a cash shortage until it becomes a real problem.
Author:James RowleySep 25, 20263 Shares37 Views
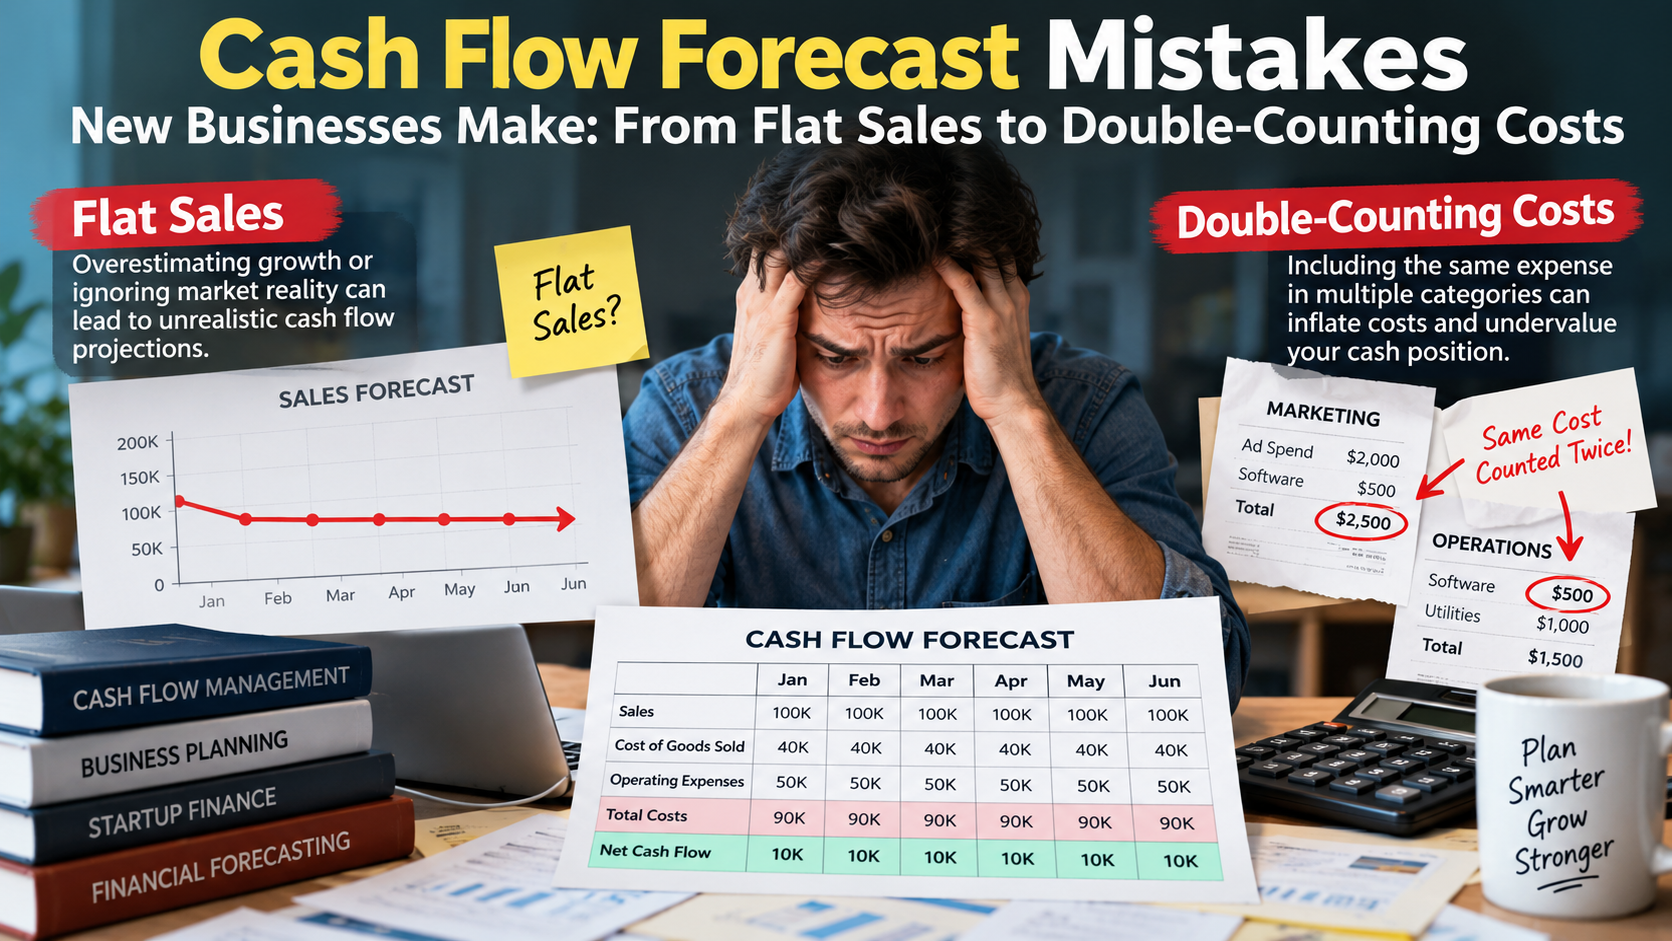
A cash flow forecast shows how money is expected to move through a new business month by month. Small errors can hide a cash shortage until it becomes a real problem. Looking at a start up loan cash flow examplecan help you understand the format, but knowing the common cash flow forecast mistakes is just as important when building your own 12-month forecast.
Why Flat Sales Figures Cause Problems
One of the biggest mistakes is flat sales volumes: using the same figure for all twelve months. New businesses rarely start at full speed, and many experience seasonal changes. A café may see a dip in January, while a shop may peak before Christmas.
For illustration, a new café might forecast £2,500 in its first month, £3,200 as awareness grows and £4,000 later in the year, rather than assuming £4,000 from the beginning.
Build a sales curve you can explain. Be conservative in the early months and explain why sales increase when they do. Break sales down by product or service where possible, using a realistic selling price, cost price and expected monthly volume.
Getting Costs Into The Right Months
A forecast needs more than a list of costs. Timing matters too. Include rent, utilities, insurance, marketing, wages and other regular expenses in the months when they actually occur.
One-off setup costs should be placed in the pre-trading period where appropriate. Recurring costs usually begin in month 1. Payment timing matters as well. A customer invoice issued in March but paid in May does not improve the March cash position.
Avoiding Double-Counting
Another common mistake is entering the same loan-related figures twice. Some planning tools automatically place the loan drawdown, loan-funded setup costs and repayments into the forecast. Check what your tool or template already includes before adding anything by hand.
The same principle applies across documents. Start Up Loan repayments belong in the business cash flow forecast, not the personal survival budget, so they should not be counted in both.
Allowing For Your Own Income Needs
If household outgoings are higher than the income that will continue after launch, the difference becomes the salary the business needs to provide. That amount should appear in the forecast, and the business needs to generate enough cash to support it.
Leaving this out can make the business appear more profitable than it really is. Build your personal survival budget first, then carry any resulting shortfall into the business forecast.
A Practical Way To Check Your Forecast
Bizbritainis an FCA-authorised credit broker and an official Business Support Partner for the Start Up Loans scheme. Its free myplan tool helps applicants build the business plan, personal survival budget and cash flow forecast through straightforward questions. It also calculates sales revenue and cost of sales from your assumptions and places the loan drawdown and repayment for you.
The tool can reduce manual calculations, but realistic products, prices, sales volumes, costs and payment assumptions still need to come from you.
Review The Numbers Before Submission
Read the forecast as if you were checking someone else's numbers. Are sales different from month to month for a reason? Are costs placed in the correct periods? Have any loan-related figures been entered twice? Does the forecast include the income the business needs to provide?
Most cash flow forecast mistakes come from flat assumptions, missing timing information or duplication. Fixing these issues before submission gives you a clearer picture of the funding the business needs and whether its expected cash position is realistic.
James Rowley
Author
James Rowley is a London-based writer and researcher covering London life, cultural geography, London travel, live London webcam pages and selected public figures across entertainment, sport, business and public life.
For over 15 years, he has focused on verified sources, first-hand local context and clear explanations that help readers understand both places and people more deeply. His work combines street-level London knowledge with careful research into career credits, media work, business interests and, where relevant, transparently explained net worth estimates.
He writes and reviews articles published on LondonWebcam.
Latest Articles
Popular Articles